The Payload Blind Spot: Why a Fully Loaded Van Can Outgrow a Cheap Policy
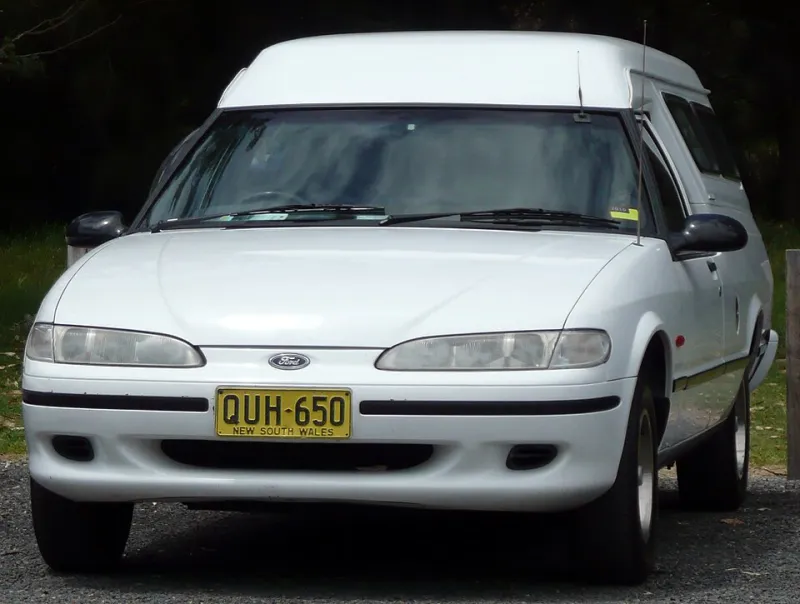
Photo: OSX, Public domain, via Wikimedia Commons
A cheap van quote is a bit like a builders' merchant estimate: it works on typical quantities. The insurer prices for a standard van doing standard van things. Then you fill it with half a pallet of tiles, a cement mixer, four bags of sand and your mate Dave. The van still starts. The brakes still work. But the policy may no longer fit the vehicle you're actually driving.
That's the payload blind spot. It's not about whether you ticked 'business use' or remembered to add a named driver. It's about the weight the van is designed to carry, the weight you've actually put in it, and whether the insurer's cheap quote was built around the same numbers.
The number stamped in the door shut
Every van has a VIN plate, usually somewhere around the door aperture, under the bonnet or on a slam panel. Among the numbers you'll find the gross vehicle weight (GVW), also called maximum authorised mass (MAM), plus axle limits and sometimes a gross train weight for towing.
GVW is the most the van can weigh when fully loaded: vehicle, fuel, driver, passengers, tools and cargo. Payload is the difference between that figure and the van's kerb weight. A van with a 3,500kg GVW and a 1,400kg kerb weight has roughly 2,100kg to play with. That sounds like a lot until you add racking, ply lining, a spare wheel, a full tank and a tail lift.
The door-shut plate is the bit to check before you buy, not after you've loaded up. A cheap quote for a 'Transit' or a 'Vivaro' is not a quote for every Transit or Vivaro ever made. The same badge can cover vans with different GVWs, payloads and axle ratings.
Why 3.5 tonnes is the line that matters
In the UK, 3.5 tonnes is the dividing line for lots of things. A standard B car licence covers vans up to 3,500kg MAM. Go above that and you're generally into C1 territory. Insurance follows a similar split: a cheap commercial van policy is usually built around a light van up to 3.5 tonnes, while heavier vans may need a different policy, different questions and a different premium.
That's why a fully loaded van can fall outside a cheap policy's assumptions even if the van itself is legally a 3.5-tonner. If you've downplated a heavier van to 3.5 tonnes to keep it on a B licence, the GVW on the plate may be 3,500kg but the payload can shrink. If you've uprated a van above 3.5 tonnes, the vehicle may now need C1 entitlement and insurance that knows about the higher weight.
Downplating isn't a loophole. It's a paperwork change that reduces the maximum weight. Uprating isn't a free upgrade either. Both can affect what you can legally carry, who can drive and what the insurer thinks it's covering.
When the load, the racking and the tail lift all count
Payload isn't just the cargo in the back. It's everything the van carries beyond its kerb weight. That includes:
- tools and toolboxes
- racking, shelving and ply lining
- spare wheel, jack and any fixed equipment
- a tail lift or loading ramp
- passengers
- fuel and fluids beyond the kerb weight figure
- the contents of the cab, including that crate of sealant you forgot about
Add a full load of materials and the numbers can stack up quickly. A van that's fine on a solo tip run can be over its GVW on the way to a job with a full kit, two passengers and a fuel tank.
Modifications matter here too. Racking and ply lining are common, but they add weight and they can be a material fact for the insurer. A cheap policy may have been priced on a standard van with no permanent fit-out. If you've added a heavy shelving system, a bulkhead or a tail lift, tell the insurer. It's better to pay a small adjustment now than to discover at claim time that the van on the policy isn't the van in the yard.
The weighbridge moment
You don't have to guess. Local council weighbridges, recycling centres and some builders' merchants have weighbridges you can use. Load the van as you would for a normal job, drive over, and compare the reading with the GVW and axle limits on the VIN plate.
Keep the ticket. It's useful evidence if anyone asks what the van weighed. It's also a reality check: if you're over the GVW, you're not just in insurance territory, you're in driving licence and DVSA territory. Overloading can affect handling, braking and tyres, and it can give an insurer a reason to look closely at a claim.
What happens at claim time
If the worst happens and you need to claim, the insurer will want to know what vehicle it was covering. If you declared a 3.5-tonne van but the plate says 4.2 tonnes, or you said 'no modifications' when there's a tail lift on the back, that's a mismatch.
Under the Consumer Insurance (Disclosure and Representations) Act 2012, insurers have to respond proportionately to careless misrepresentation. That doesn't mean everything is fine. It can mean a reduced payout, additional terms or, in serious cases, a policy that doesn't respond as you expected. Deliberate or reckless misrepresentation can be worse.
The practical point is simple: a cheap premium is only cheap if the policy actually covers the van you drive, loaded the way you load it. A claim-time reduction can wipe out years of savings.
Checks before you buy or load up
Before you buy a van, check the VIN plate and the handbook. Ask the seller what the GVW and payload are, and don't rely on the model name alone. If you're buying from a dealer, get the weights in writing.
Before you renew or switch, tell the insurer the GVW, any modifications and what you typically carry. Ask them to confirm the van's weight class is on the policy. If you're planning to uprate or downplate, talk to the insurer before the paperwork changes, not after.
And before a big load, use a weighbridge. It's a lot cheaper than finding out at claim time that your cheap cover was priced for a lighter van.
VanCoverCheap's take: cheap van insurance can be genuinely good value, but it works best when the numbers match. The VIN plate is boring. The weighbridge is inconvenient. The claim conversation is worse.